
Fully occupied. Every tenant below market. Anchor lease expires in two years.
What’s your take on this deal?
A few days ago, I posted a deal and asked what you’d offer. Here’s my take.
Those of you who have done a deal or two know that there is no such thing as a single correct price. Maybe a best estimate, but certainly not a sure-fire right answer. What if expenses grow faster than we projected? Or the exit cap rate compresses or expands? Or a meteor strikes your office and wipes out your hard drive? Stuff happens.
This solution presents a suggested offer of $875,000 and explains some of the reasoning behind it. You may come up with a different amount, and that’s ok – provided you have reasons you can explain.
Start with what the rent roll is telling us
Before building a pro forma, we should examine the lease structure for what it tells us about risk and opportunity. Every tenant is below market, and two of the four leases require attention within the first two years of your hold. That’s not a coincidence — it’s why this property will show a high entry cap rate at any reasonable asking price. The cap rate isn’t a gift. It’s compensation for lease rollover risk. Unit A is the one to watch. At $18/SF against a $24 market, it has the largest below-market spread in the building, and the lease expires at the end of Year 2. Unit C is already month-to-month. Units B and D are locked in and anchor your income stream.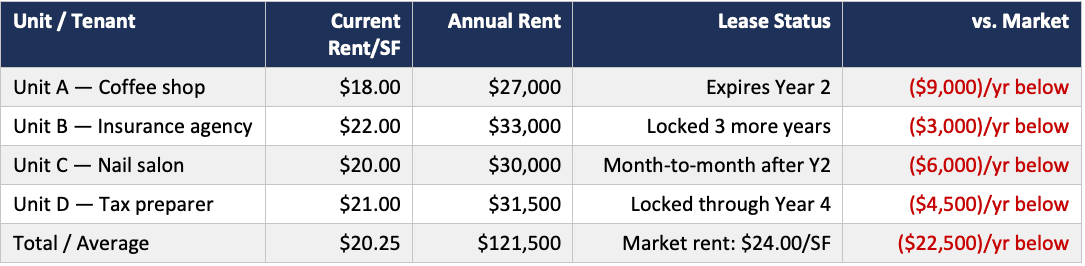
Year 1 NOI — before we pick a price
Calculating the NOI is usually a good place to start. The $3,000 CapEx reserve is contributed at closing and recovered at resale — so it’s not part of NOI, and it doesn’t reduce annual cash flow.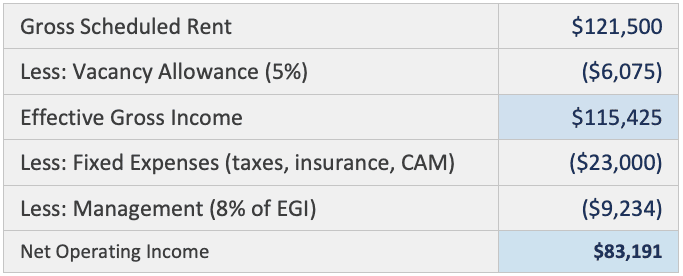
Deriving an offer price
Two approaches, used together. Income capitalization: Comparable stabilized properties are trading at 7–8% cap rates. This property carries rollover risk, so a risk-adjusted cap of 8.5–9.5% seems appropriate:- At 8.5%: $83,191 ÷ 0.085 = $978,718
- At 9.0%: $83,191 ÷ 0.090 = $924,344
- At 9.5%: $83,191 ÷ 0.095 = $875,694
Financing at $875,000 purchase price
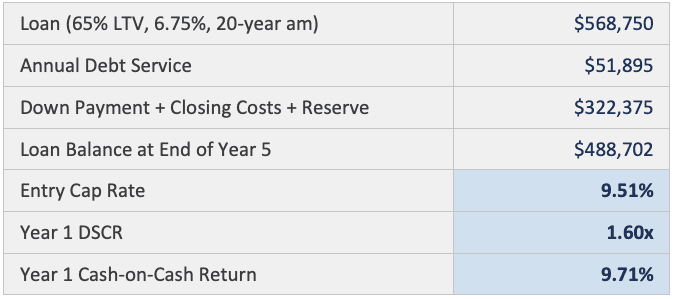
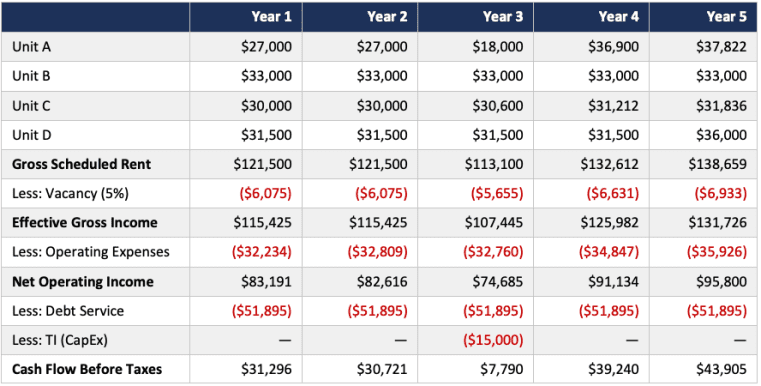
Base case pro forma
Here is where we need to think about this deal from the point of view of a real participant and make some realistic assumptions as to how our revenue and cash flow might play out.- Unit A goes vacant for six months in Year 3 before re-leasing at market, with a $15,000 TI allowance charged as CapEx.
- Unit B’s lease is locked in through Year 4. We decide to hold Year 5 rent at $22/SF. At $2/SF below market, the tenant has a clear incentive to renew, and the conservative flat-rent assumption avoids overstating exit NOI.
- Unit C stays on modified month-to-month terms, averaging a 2% increase.
- Unit D renews at market in Year 5.
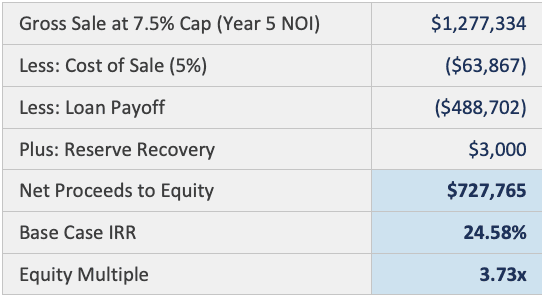
What if things go better — or worse?
We modeled the $875,000 price under three lease outcome assumptions: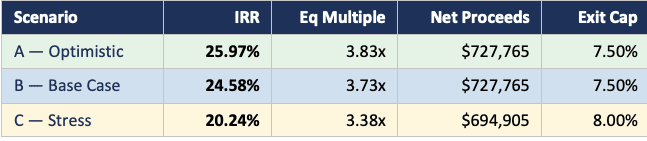 The spread between optimistic and stress is about 5.7 percentage points — driven almost entirely by lease assumptions, not market conditions.
Sensitivity analysis
Price sensitivity (base case leases, 7.5% exit cap):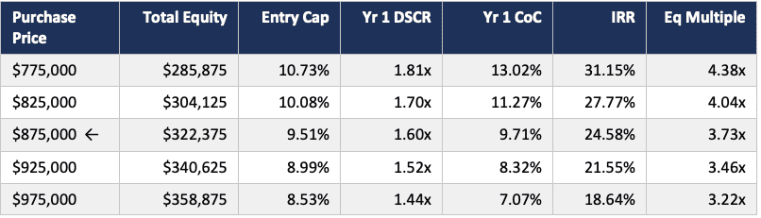 Exit cap rate sensitivity ($875,000, base case leases):
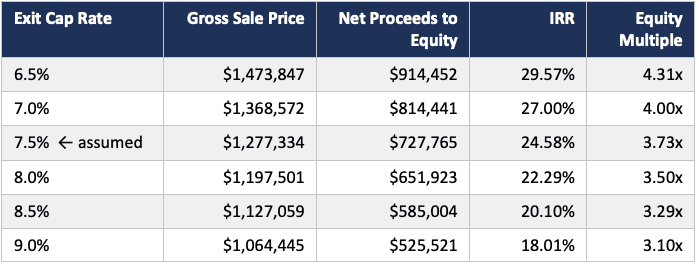 A 100 basis point expansion in the exit cap rate costs about 4.5 points of IRR. That’s a risk you can’t control — where cap rates are in five years.