podcast listener

I have several ebooks that I send out at no cost to folks who sign up for our “insights” mailing list. But in today’s hyperspeed world, I’m finding that now a lot of people who are constantly on the go just don’t have time to sit and read as much as they’d like. That’s why, with help of my AI sidekick, I’ve started turning the content of those ebooks into podcasts.

Follow this link to listen to the first. And stayed tuned for several more.

https://www.realdata.com/realestateeducation/5_Key_Steps_podcast.mp3
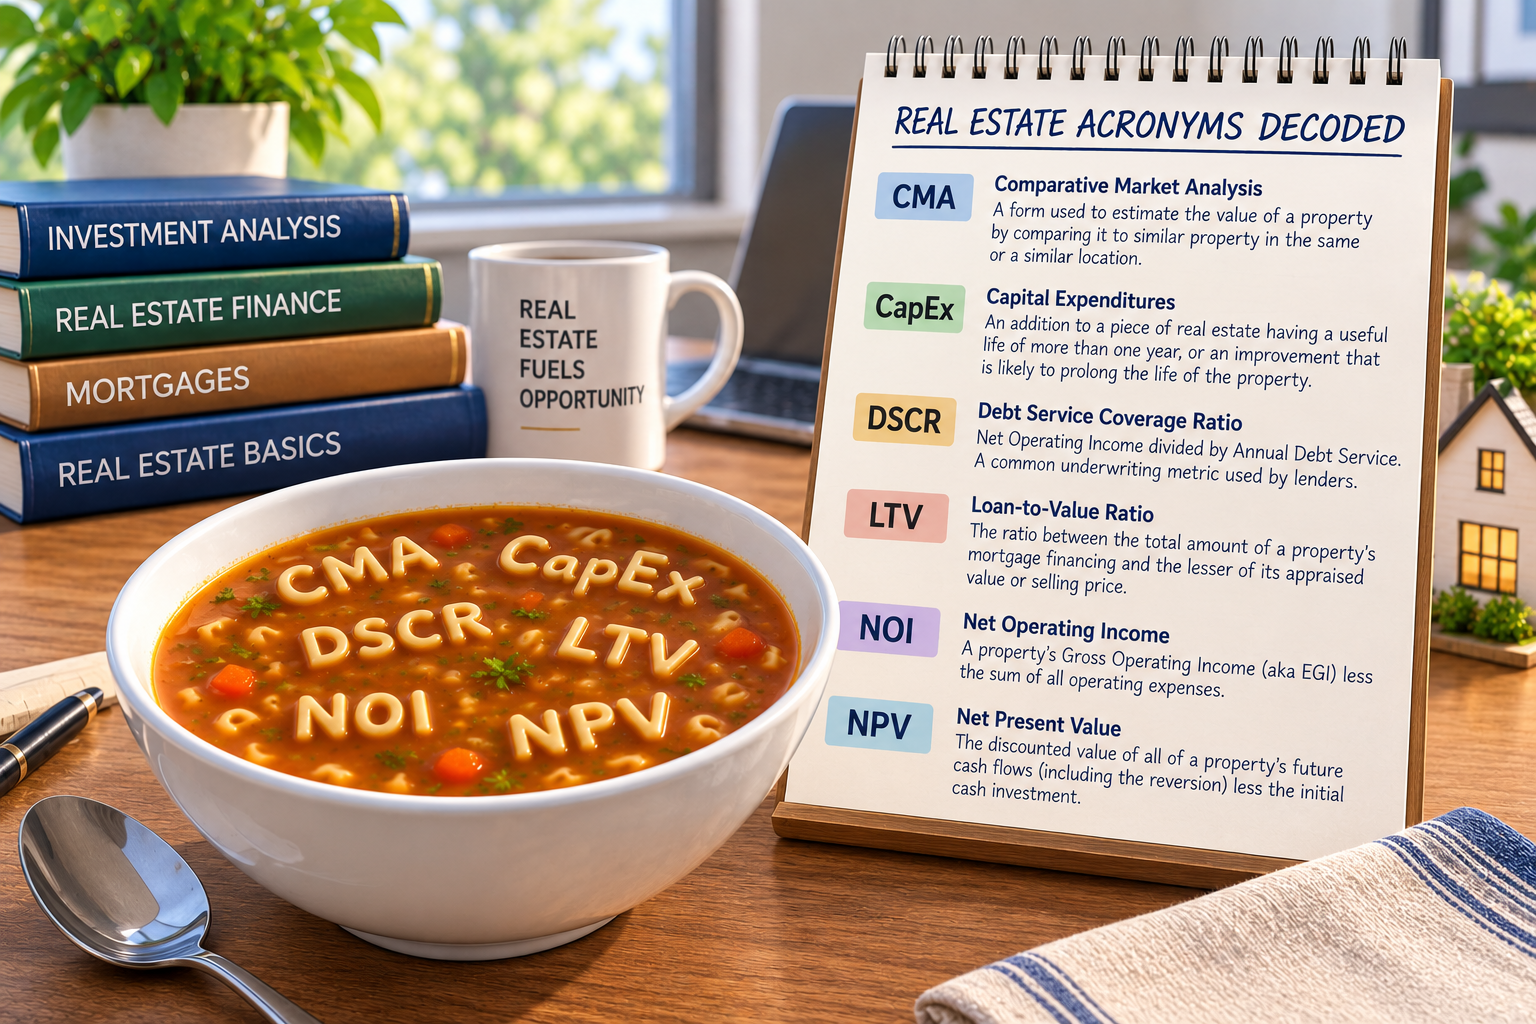
In my previous post, I gave you a list of some of the most common acronyms used in real estate. Not a complete list, of course, but a good start to decode the secret jargon of our industry.

And as I professed then,  mastering this lingo and using these terms correctly not only facilitates communication but also demonstrates expertise and insider knowledge.

Now that we have a representative list, let’s look at the meaning of some of these terms.

Self-Storage Investing, commercial real estate analytics software

In my previous post, I discussed what I believe are some of the most important pros and cons of investing in self-storage real estate.

As with most real estate sectors, self-storage features some terms that are particular to this property type — specifically in how owners describe occupancy: Unit Occupancy, Physical Occupancy, and Economic Occupancy. Let’s review them:

highwire act

Leverage is a fundamental tool in real estate investing, allowing investors to acquire properties while using their own cash for just a fraction of the total cost. Borrowing money to invest in income-producing properties can amplify your returns, allowing you to scale faster than relying solely on your own capital. However, excessive leverage can prove to be a double-edged sword—when the market is in your favor, it opens the door to greater opportunity. But if the market turns against you, it can lift the lid on Pandora’s box. In this article, I’ll explore the benefits and some of hidden dangers of high leverage, how it can impact long-term investment success, and ways to strike the right balance.

You’ve been watching the markets lately. How could you avoid it? You know the story: wild stock swings; headlines driving fear; nonstop chatter about tariffs, recession, interest rates, and global trade. It’s a jungle out there.

But amid all the noise, one thing hasn’t changed—and likely never will: real estate remains one of the smartest, most stable paths to building long-term wealth.

Mistakes That Real Estate Investors Should Avoid, real estate investment evaluation

Real estate has probably been the best vehicle for building wealth since, well, forever – and income-producing real estate (aka rental property) may be the type of real estate that offers the greatest opportunities to small and mid-size investors.

But nothing worthwhile comes without a few potential pitfalls. You can and certainly should prosper as an investor, but to do so means being mindful of some mistakes that could derail your success. Let’s consider a few of the most important:

Calculating Internal Rate of Return, real estate investment evaluation software

Users of our Real Estate Investment Analysis program sometimes call us with questions that are not about the software but about the underlying analysis. If we had a “greatest hits” list for those questions the all-time winner would be this: “My cash flow goes up each year; the value of the property goes up each year; but when I look at the Internal Rate of Return, it goes down almost every year. What’s up with that?” To see how this can happen, let’s take a look at two very simple examples.

laptop with regression analysis graph, real estate investment analysis

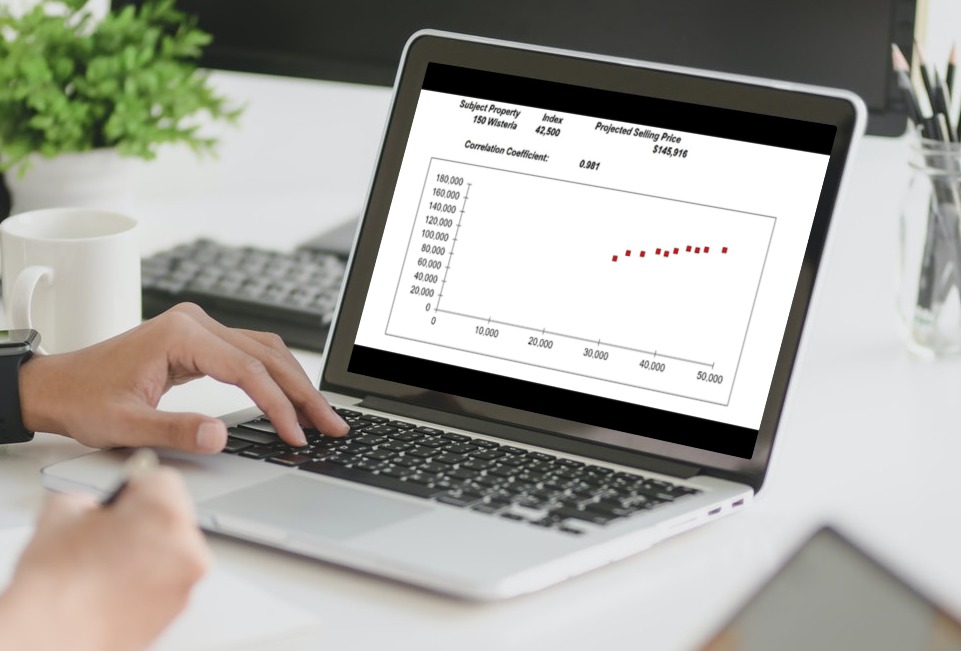
Regression – no, it’s not what your family and friends accuse you of when you want to trade in the mini-van for a two-seater stick-shift convertible (well, maybe it is, but that’s a topic for a different article). If you’re familiar with our RealData software, my online video courses, and my other blog posts here, then you know that I’m usually talking about income-producing property like multi-family, retail, office, or the like — seldom about single-family homes. And when we estimate the value of most income properties, we typically do so by looking at their income stream.