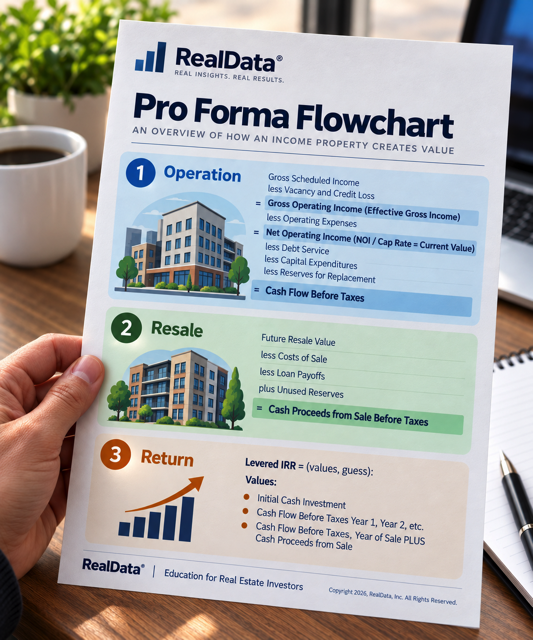
Give AI a properly constructed series of prompts and you get an operating statement you can check, a five-year projection, and an exit price. You also find out which assumption the return depends on, and that is is often not the one the broker is talking about. Here’s how this works on a realistic multifamily deal, a six-unit apartment building, and where the analysis pays for itself.
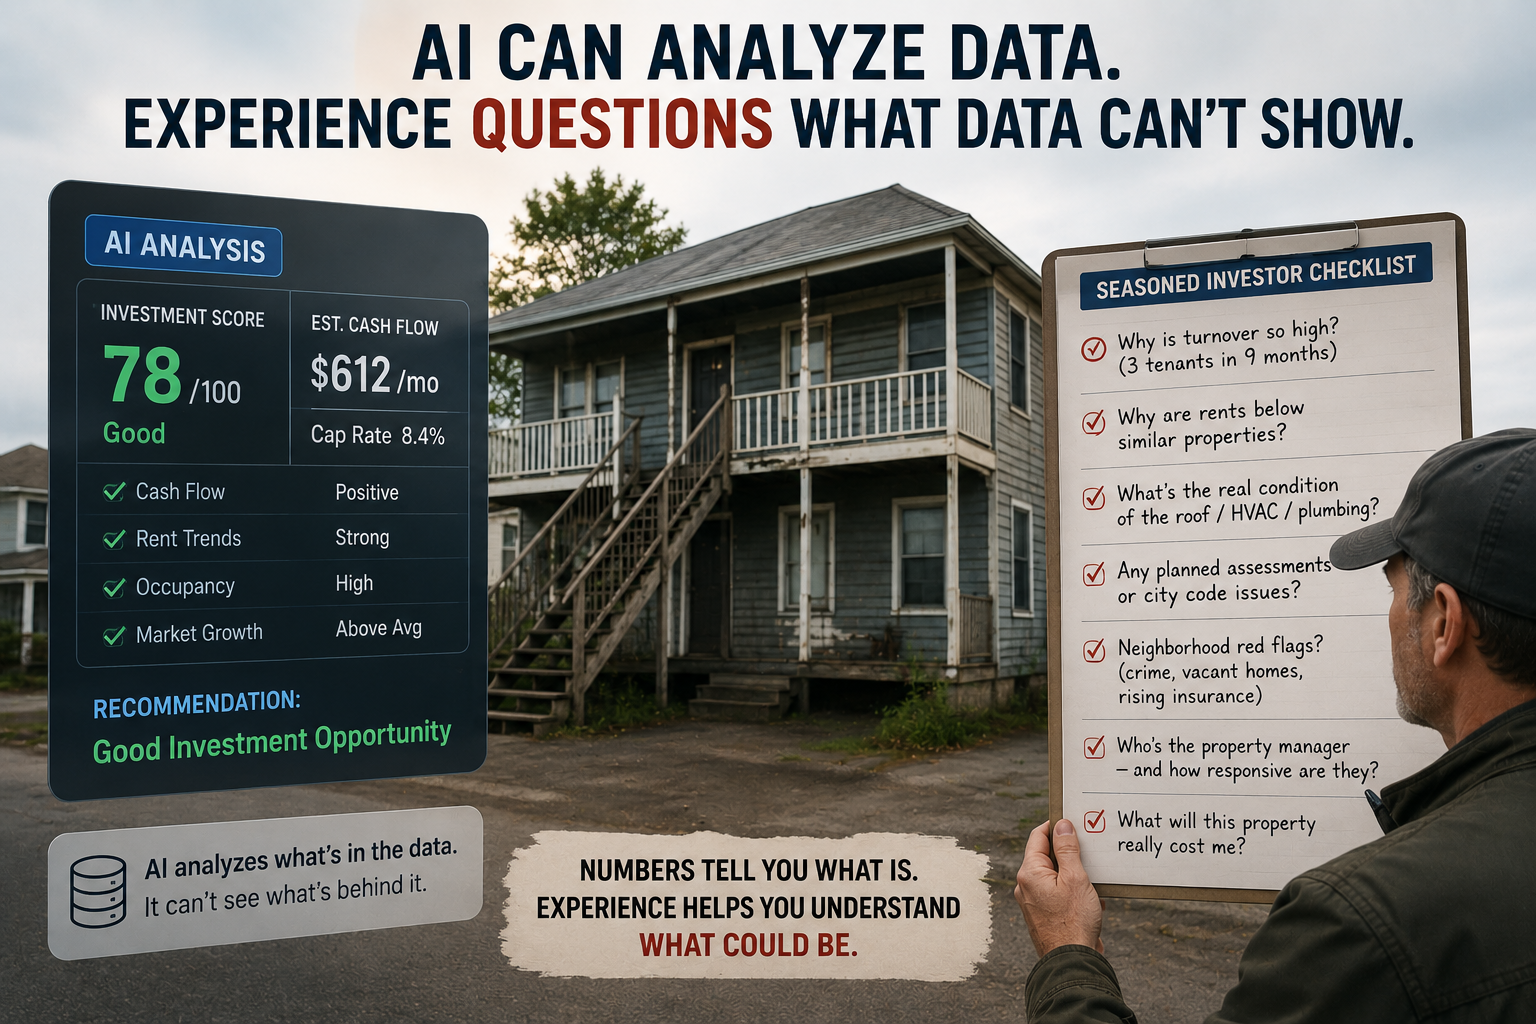
AI vs reality for an income property investment

Paste a listing into an AI tool and you’ll get a slick analysis in seconds — cap rate, cash-on-cash, a confident verdict. It might also be wrong in ways that really matter. AI has changed a lot about how we analyze income property. What it hasn’t changed is who wins and who loses.

Those of you who have done a deal or two know that there is no such thing as a single correct price. Maybe a best estimate, maybe a range of possibilities, but certainly not a sure-fire right answer.

I’ll walk you through my approach, step-by-step, to zeroing in on a price that might be acceptable.

I’ve done a good deal of teaching about the process of underwriting real estate investments, particularly income-producing properties. I’ve seen some good approaches and some not so good.

Chances are, if you’re doing a pro forma workup, it’s not just for your own benefit, but also to convey your point of view to a third party. You might be telling the seller or a potential lender, “Here’s what I think is a fair price for this property, and why.”

A few days ago I posted a deal like the ones I give my students and asked what you’d offer.

Those of you who have done a deal or two know that there is no such thing as a single correct price. Maybe a best estimate, maybe a range of possibilities, but certainly not a sure-fire right answer.

I’ll walk you through my approach, step-by-step, to zeroing in on a price that might be acceptable.

Recently, I had the pleasure of being a guest on a podcast hosted by Asa Moran, a real estate student at the University of Alabama. Asa is one of a growing wave of bright, motivated students who are preparing to make their mark in the commercial real estate world.

As some of you know, I’m a big believer in supporting the next generation of investors.

During the podcast, we covered a lot of ground, from cash flow fundamentals to the nuances of value-add strategies.

At RealData, we’ve seen an uptick in interest about expense reimbursements, aka pass-throughs or recoverable expenses. If you’re in commercial real estate—whether as an investor, broker, property manager, or tenant rep—then you know that such reimbursements can make or break a deal. That’s why I’m giving away a FREE eBook: “Understanding Real Estate Expense Reimbursements.”

Calculating Modified Internal Rate of Return, real estate investment calculators

Internal Rate of Return (IRR) is the metric of choice for many, if not most, real estate investors. But there are a few issues with IRR that can cause you some vexation: If you expect a negative cash flow at some point in the future, then the IRR computation may simply fail to come up with a unique result; and with your positive cash flows, IRR may be a bit too optimistic about the rate at which you can reinvest them.

For these reasons, a variation on IRR, called Modified Internal Rate of Return (MIRR), can be a useful tool. Let’s see how it works, and see how it gives you the opportunity to deal with IRR’s shortcomings.