Investing in Self-Storage Real Estate: Pros and Cons
Simply put, self-storage properties are built to contain many, often hundreds of individual storage spaces of varying sizes. It’s a booming market, forecast to be worth over $64 billion by 2026.
Home » Insights
For more than 40 years, RealData has helped real estate investors and developers navigate the road to success.
Our mission is twofold: To supply the software tools you need to evaluate commercial, residential and mixed-use income-property investments, projects and partnerships; and to provide you with the educational materials and resources to be a knowledgeable investor.

Simply put, self-storage properties are built to contain many, often hundreds of individual storage spaces of varying sizes. It’s a booming market, forecast to be worth over $64 billion by 2026.

The rise of home-sharing platforms like Airbnb has been a boon to property owners, especially owners of smaller income properties, but it has also prompted municipalities to introduce regulations on short-term rentals (STRs). Many places impose restrictions, such as requiring permits or licensing, limiting occupancy, and restricting the number of days permitted.

Leverage is a fundamental tool in real estate investing, allowing investors to acquire properties while using their own cash for just a fraction of the total cost. Borrowing money to invest in income-producing properties can amplify your returns, allowing you to scale faster than relying solely on your own capital. However, excessive leverage can prove to be a double-edged sword—when the market is in your favor, it opens the door to greater opportunity. But if the market turns against you, it can lift the lid on Pandora’s box. In this article, I’ll explore the benefits and some of hidden dangers of high leverage, how it can impact long-term investment success, and ways to strike the right balance.

The new 2025 tax law keeps many of TCJA’s key provisions in place—some permanently, others with long-term extensions, and also brings a mix of permanent changes, updated incentives, and new planning opportunities

You’ve been watching the markets lately. How could you avoid it? You know the story: wild stock swings; headlines driving fear; nonstop chatter about tariffs, recession, interest rates, and global trade. It’s a jungle out there.
But amid all the noise, one thing hasn’t changed—and likely never will: real estate remains one of the smartest, most stable paths to building long-term wealth.

Real estate has probably been the best vehicle for building wealth since, well, forever – and income-producing real estate (aka rental property) may be the type of real estate that offers the greatest opportunities to small and mid-size investors.
But nothing worthwhile comes without a few potential pitfalls. You can and certainly should prosper as an investor, but to do so means being mindful of some mistakes that could derail your success. Let’s consider a few of the most important:

For those of us whose experience with rental property goes back a few decades (maybe even more than a few), the term “property management” conjures up images of ledger books for recording rent payments and expenses, receipt pads for tenants who paid by cash, and a plumber or two on our landline’s speed dial.

Users of our Real Estate Investment Analysis program sometimes call us with questions that are not about the software but about the underlying analysis. If we had a “greatest hits” list for those questions the all-time winner would be this: “My cash flow goes up each year; the value of the property goes up each year; but when I look at the Internal Rate of Return, it goes down almost every year. What’s up with that?” To see how this can happen, let’s take a look at two very simple examples.

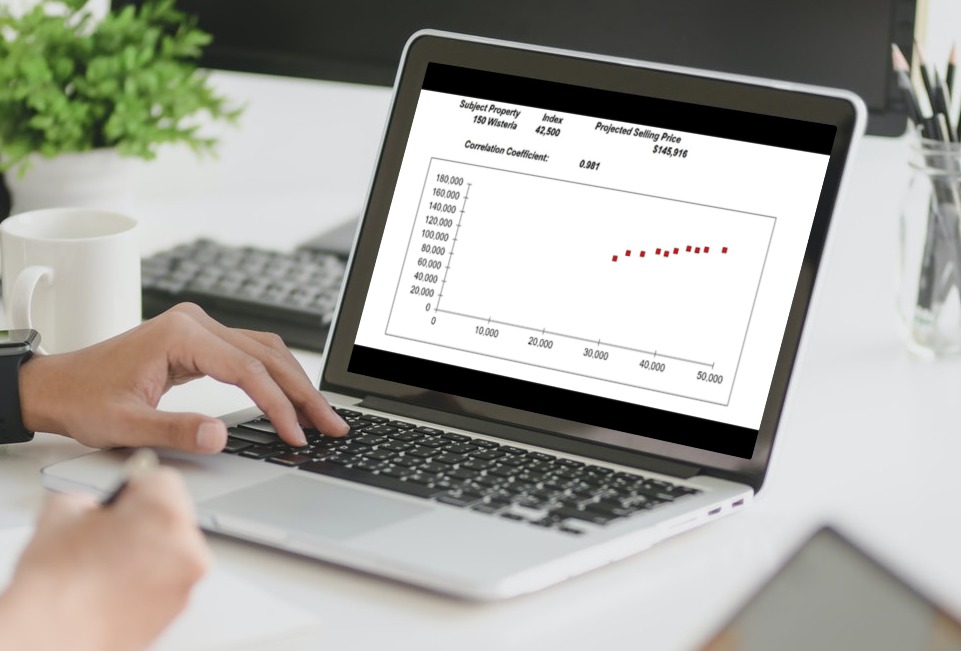
Regression – no, it’s not what your family and friends accuse you of when you want to trade in the mini-van for a two-seater stick-shift convertible (well, maybe it is, but that’s a topic for a different article). If you’re familiar with our RealData software, my online video courses, and my other blog posts here, then you know that I’m usually talking about income-producing property like multi-family, retail, office, or the like — seldom about single-family homes. And when we estimate the value of most income properties, we typically do so by looking at their income stream.

We usually think of Return on Equity (ROE) as a straightforward investment measure. That’s understandable, because the traditional method of calculating ROE is pretty clear cut: Take your cash flow after taxes and divide it by your initial cash investment.

We hear all the time that users of our RealData investment analysis software are tuned in to any changes in the interest-rate envrionment.
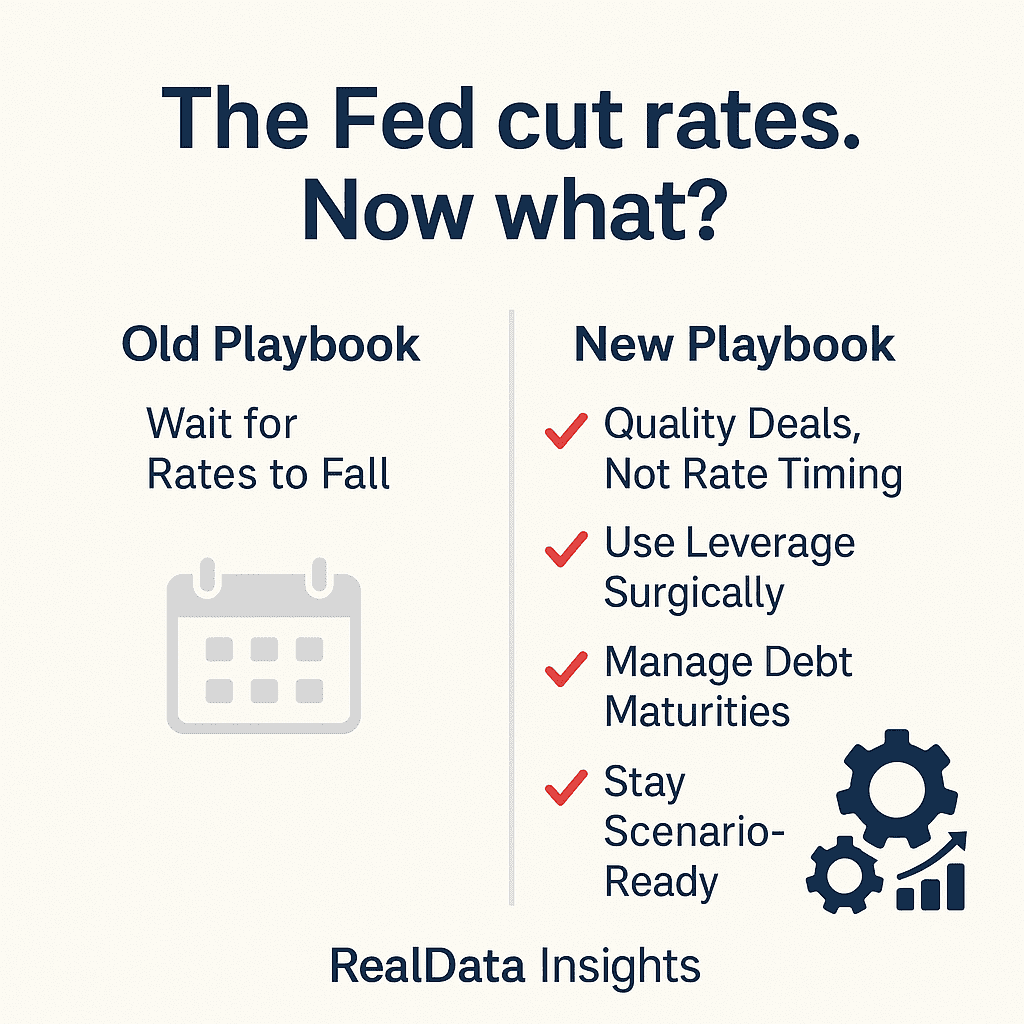
Well… the Fed finally blinked. After two years of hikes that drove borrowing costs through the roof, the central bank cut its policy rate to 4.00%–4.25% in September. Good news, right?
disappeared. In other words: lower Fed rates don’t automatically translate into cheap financing or sky-high property values.
This is a market where “wait for rates to fall and then buy” doesn’t cut it anymore. The smart money is shifting from timing to structuring. Let’s break down what’s really happening—and how real estate investors might choose to play it.
One topic that often gets less attention than it deserves from real estate investors, however, is resale. Some tend be dismissive, looking at resale as speculation, but many others simply find it difficult to focus seriously on the matter of selling a property they haven’t yet purchased.It may take a little extra discipline to work a consideration of resale into your investment mindset, but it is just such discipline that often separates the successful investor from the sorry.