Most real estate investors learn about capitalization rate (cap rate) early on—and for good reason. It’s a useful, at-a-glance measure of a property’s income in relation to its market value.

But cap rate has its limitations: it reflects only a single year of net operating income (NOI), ignores financing, and says little about long-term performance. It looks at a property at a point in time, not over the long term.

If you’re serious about evaluating income-producing real estate—especially in a competitive or uncertain market—you need to go deeper. In this article, I’ll walk you through five advanced metrics that provide a more comprehensive and strategic view of a commercial investment’s potential. Ready for that deeper dive?
Many of my articles here on RealData Insights have focused on the front end of income property investing — projecting cash flows and weighing the metrics that separate a potentially strong investment from one that falls short. It is easy to get wrapped up in the metrics of this process and to forget that eventually you’ll have to engage in the human and sometimes demanding business of actually managing the property you buy.

How you fulfill that task can go a long way toward determining the financial success of your investment. Property management can be a complex subject, but if you observe some basic principles you can maximize your long-term profit and minimize some of the burden.

You’ve been watching the markets lately. How could you avoid it? You know the story: wild stock swings; headlines driving fear; nonstop chatter about tariffs, recession, interest rates, and global trade. It’s a jungle out there.

But amid all the noise, one thing hasn’t changed—and likely never will: real estate remains one of the smartest, most stable paths to building long-term wealth.

real estate investor's playbook

We hear all the time that users of our RealData investment analysis software are tuned in to any changes in the interest-rate envrionment.

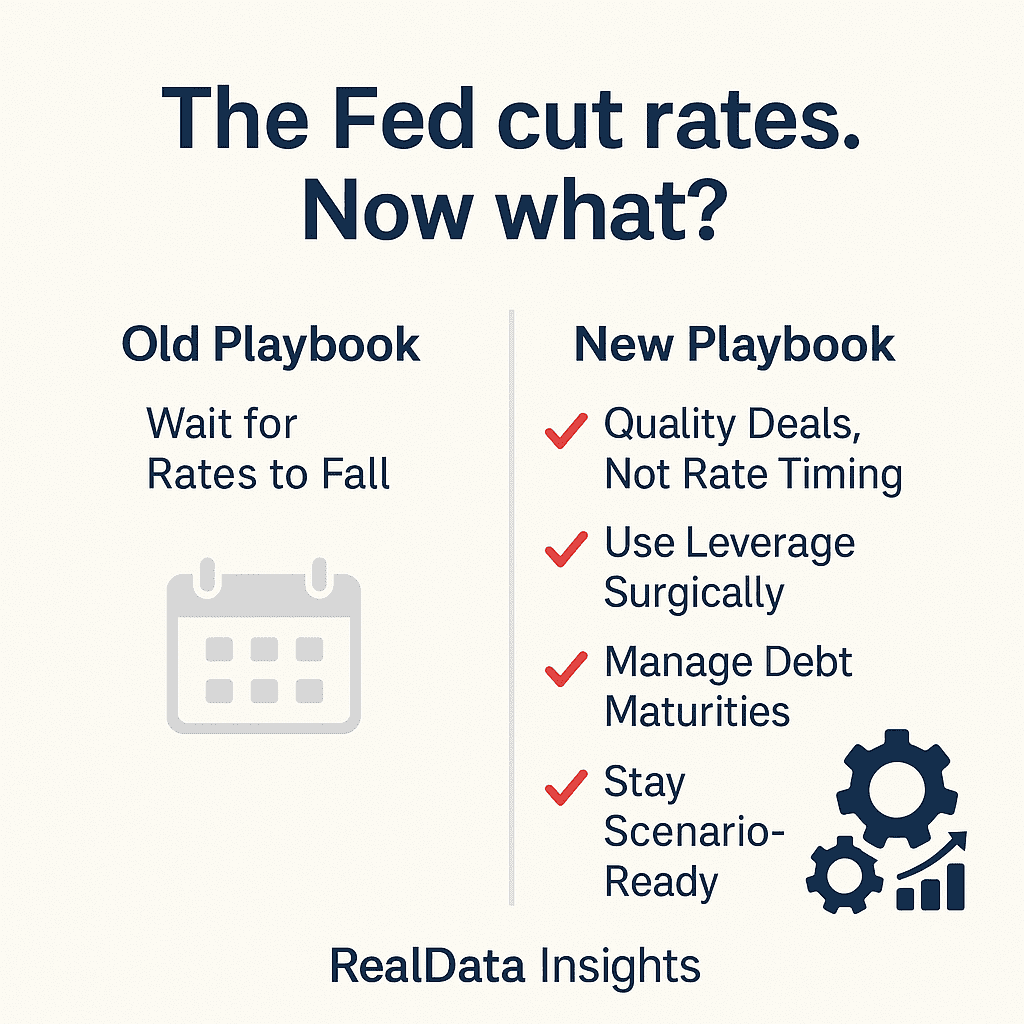
Well… the Fed finally blinked. After two years of hikes that drove borrowing costs through the roof, the central bank cut its policy rate to 4.00%–4.25% in September. Good news, right?

disappeared. In other words: lower Fed rates don’t automatically translate into cheap financing or sky-high property values.

This is a market where “wait for rates to fall and then buy” doesn’t cut it anymore. The smart money is shifting from timing to structuring. Let’s break down what’s really happening—and how real estate investors might choose to play it.

Whitish mouse

I remembered a day when I was an undergrad psych major at Yale (a day in 1964, if you can believe) when my professor did an experiment in class that stayed with me for all these years.

He had a little mouse and what looked like a Skinner Box – you might remember those from your college years, an enclosure designed to use positive reinforcement – receiving food pellets in a tray – to teach the mouse to perform some action, like pressing a lever.

The prof came into our lecture hall in front of a hundred or more bright-eyed freshman carrying a modified version of the box: It had two separate levers that would each deliver food pellets, and one of the levers was designed to pay off much more frequently than the other.