Calculating Internal Rate of Return, real estate investment evaluation software

Users of our Real Estate Investment Analysis program sometimes call us with questions that are not about the software but about the underlying analysis. If we had a “greatest hits” list for those questions the all-time winner would be this: “My cash flow goes up each year; the value of the property goes up each year; but when I look at the Internal Rate of Return, it goes down almost every year. What’s up with that?” To see how this can happen, let’s take a look at two very simple examples.

laptop with regression analysis graph, real estate investment analysis

Regression – no, it’s not what your family and friends accuse you of when you want to trade in the mini-van for a two-seater stick-shift convertible (well, maybe it is, but that’s a topic for a different article). If you’re familiar with our RealData software, my online video courses, and my other blog posts here, then you know that I’m usually talking about income-producing property like multi-family, retail, office, or the like — seldom about single-family homes. And when we estimate the value of most income properties, we typically do so by looking at their income stream.

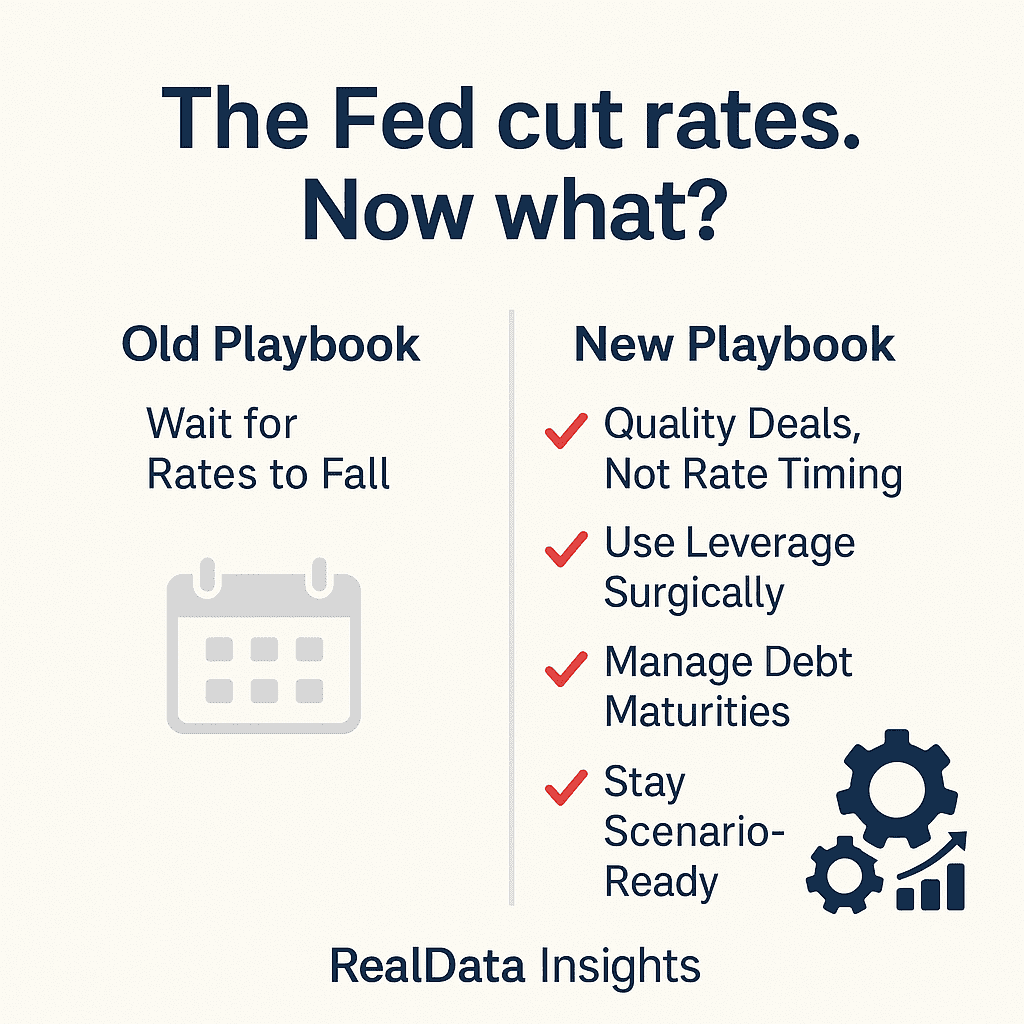
real estate investor's playbook

We hear all the time that users of our RealData investment analysis software are tuned in to any changes in the interest-rate envrionment.

Well… the Fed finally blinked. After two years of hikes that drove borrowing costs through the roof, the central bank cut its policy rate to 4.00%–4.25% in September. Good news, right?

disappeared. In other words: lower Fed rates don’t automatically translate into cheap financing or sky-high property values.

This is a market where “wait for rates to fall and then buy” doesn’t cut it anymore. The smart money is shifting from timing to structuring. Let’s break down what’s really happening—and how real estate investors might choose to play it.

Return on Equity, real estate data analytics software

One topic that often gets less attention than it deserves from real estate investors, however, is resale. Some tend be dismissive, looking at resale as speculation, but many others simply find it difficult to focus seriously on the matter of selling a property they haven’t yet purchased.It may take a little extra discipline to work a consideration of resale into your investment mindset, but it is just such discipline that often separates the successful investor from the sorry.

Cash-on-Cash Return in Real Estate, software for real estate investing

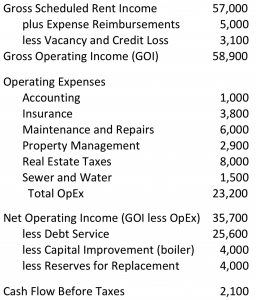
In the first part of our discussion, you looked at the simple math that underlies Cash-on-Cash Return. The short version goes like this: First you calculate your property’s first-year cash flow before taxes—essentially all the cash that comes in from operating the property minus all the cash that goes out. Then you divide that by your initial cash investment, and that percentage is your Cash-on-Cash Return. Nothing could be simpler.

Replacement Reserves Real Estate, lease rollover

It may sound like a nit-picking detail: Where and how do you account for “reserves for replacement” when you try to value – and evaluate – a potential income-property investment? Isn’t this something your accountant sorts out when it’s time to do your tax return? Not really, and how you choose to handle it may have a meaningful impact on your investment decision-making process.

Return on Equity, real estate data analytics software

In Part 1 of this article, you learned what information you need to assemble to get started with the process of refinancing your commercial property — information about your property’s income, expenses and loan balance, and about the prevailing cap rate in your market. You also learned to use some of that information to estimate the current value of the property, then learned to take that result to determine if the property will likely satisfy the lender’s Loan-to-Value requirement. You got acquainted with Debt Coverage Ratio and mortgage constants and saw how to combine those to test your property’s income stream to find out if it’s strong enough to support your loan request.